Friday, February 24, 2006

Short, but what variety.

Short, but what variety.
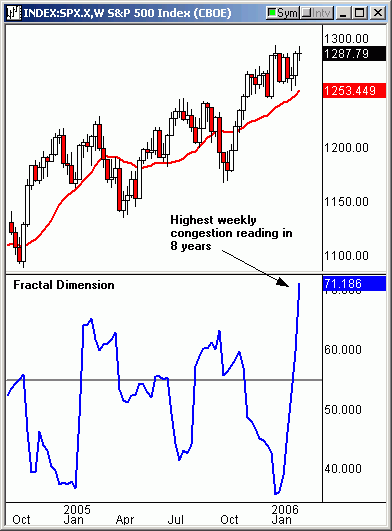
The markets are fully congested and ready for a big move. We believe this the move is going to be a strong down move and will position accordingly. There are lots of options to do this:
Sell Calls
Buy Puts
Combination of the above
Thursday, February 16, 2006

Fool AKAM post

http://boards.fool.com/Message.asp?mid=23716775

Hi Tim

Firstly, thanks for the fantastic analysis and continued thought on Akami.

After your initial recommendation, I quickly jumped on board for the following reasons.

  • High fixed costs business with expanding sales, resulting in expanding profitability, i.e. more of there sales fall straight to the bottom line.
  • Although there are some competitive risks, I saw and still see 2006 as the first breakout year for web downloads, on the road to downloads that will dwarf those of today. There needs to be some Moore like formula for web downloads, maybe Akami’s formula.

So I saw a company in the sweet spot, a spot that should get sweeter over the next year or two. With this P/E should expand as more coverage and enthusiasm builds, so expanding earnings with rising P/E multiple can only mean big price increases.

So where are we now,

EPS TTM .52

Price 02-16-06 26.67

P/E TTM 51

EPS high est 06 0.71 ( a 36% increase)

P/E forward 37.6

EPS high est 07 0.94 ( year on year 32% increase)

P/E forward 2 28.37

Looking at this makes me think a few things:

  • Are analyst’s estimates too low? With AKAM expanding sales and margin could they blow these numbers away? Maybe.
  • If they meet estimates then in two years at today’s price they would still have a P/E of 28. As they had been growing at 30%+ for a number of years they may be rewarded with a higher P/E, lets say 40, putting price around $37.
  • What happens if they have one missed estimate, Google starts to move in, Apple gives them the flick or general market conditions deteriorate? P/E will compress as investors enthusiasm wanes, lets say it comes down to TTM P/E of 30. That would take the price back to $16, using forward eps of .71 price would be $21.

Other thought:

  • I agree with Tim Hart, Google will start finding things harder. They don’t have trust. Heck I don’t trust them, even though I use their sites everyday. So why don’t I trust them? Probably, as in desperation their competitors have started spreading rumours and innuendoes about their motives. I have no real reason to distrust them, but just like Microsoft I do. Is big bad?

Disclosure: I own AKAM and recently traded Feb 25 Calls for a profit of .50. I am now looking at August Calls.

Wednesday, February 15, 2006

Roll CRYP or be called

CRYP Feb 20 Call.
The story here is different than AKAM, as it will definitely be called in 2 days and we will still own 300 shares. CRYP has had an excellent run from its lows to current 23.59 USD Up 1.27 (5.69%)


  • Dividend coming due. US$0.07 per common share. The dividend will be paid on March 15, 2006 to shareholders of record as at March 8, 2006. The ex-dividend date will be March 6, 2006
  • Looks like can only get .1 - .4 credit. Even at .4 and with dividend covering trading costs, it is only a 2% return for risk of holding.
Roll at .4 credit, as $320 (2%, annual 24%) is worth the downside risk.

Should I roll that AKAM Call

AKAM Feb 25 Call expires in 3 days, should I roll it as current 25.10.
  1. May or may not be called, but I want to make decision, not let market make it.
  2. Capital Gains, when did I buy? 27/07/2005 so to far, but should consider Aug Calls, to see.
  3. Is call for entire holding, ie will I still profit in any further upside? Yes entire 500.
  • Mar Call credit - .80. or $385 Net, for 30 days on $25 OR 3.2%, annual 38%
  • May Call credit - 1.85, 93 days, 7.4%, annual 29%
  • Aug Call credit - 2.7, 184 days, 10.8%, annual 21%
Go for Aug Call, as if price rises substantially can buy back option after 27/07 and sell shares with capital gain concession.
If share neutral then made 21% annual return.
If share falls can buy back option for cheaper and sell share, so limits downside risk.

Down side little participation in upside, need to investigate further to decide on upside potential.
The figures are:
P/E (TTM) 48.88 P/Sales 13.38

P/E (Forward) 35.31 P/Cash Flow 45.73

Earnings/Share (EPS) 2.2 Book Value/Share 4.11

PEG 1.35 P/Book 6.07

Debt/Equity 0.32 Cash Flow/Share 0.55

Yes AKAM is a cash machine with digital delivery. Digitial delivery is gonna explode, but Google is about to pounce and all it takes is one hiccup for price to slide.

Sell AUG Call, look to sell March Put.

Monday, February 13, 2006

Sitting Tight

Hold Telstra and NAB. Stories are improving at both. Sell NAB calls if good oportunity.

Friday, February 03, 2006

Confused? I am...but holding steady

The trust's US account continues to outperform the main US indexes. The account in now about 18% in cash and has a short term aim of 25% cash until the picture clears in the US. Despite the large cash holding the trust has still been outperforming during up weeks. The main reason for this is superior stock selection based on Motley Fool recommendations combined with option trading to generate income for the account.

David Nicholls projects a weekly close below 1261 will move markets in to secular bear with a 25% drop in to 4 year low in October 06. Well 950 on S&P would be scary, if this does occur the trust will be big buyers at that point. The cash holding has been built up with this downside risk in mind. As we are still invested 80% we will profit if market continues higher.

On the positive side Stealth Stocks Dennis Slowether (sp?) and McMillan are pointing for an up year. Analysts are pointing to International stocks heading higher and US stocks lagging.

The trust is happy with their current positioning and looks to decrease holding on further rises.

Thursday, February 02, 2006

Holding Telstra

The Trust will continue to hold Telstra. The latest pop in share price on news of T3 in encouraging that the trustees original investment thesis will be fulfilled. The trust will be able to sell some of it's holding over the average paid and will have netted the attractive dividends for that period. Despite being in the troubled Telecommunications industry the trustees had believed if as the largest shareholder the government had known any information that would have led them to believe $5.25 for not a realistic price for T3 then they would have stated that and lowered their price accordingly. However, despite having the knowledge they did not lower their price target. This resulted in the Trusts purchase of a volume and portfolio percentage of the shares far greater than they would normally allocate to an individual share. The other contributing factor was the announcement of the special dividend combining to form $.40 a year in franked dividend. Was that a bribe to unload shares by the company?

At any rate the dividend has been better than interest and as stated the trustees believe they will get to sell above the average price, some time in the future. They will look at call options on Telstra.

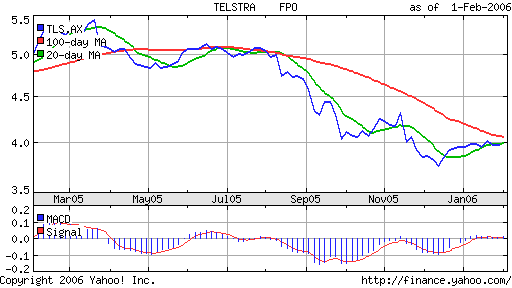
Near term technical positive developments would be 20 day cross 100 day, MACD rise above zero, ie share price go up.

Fundamental improvements looked for : Positive wireless and broadband trends, T3, dividend maintained, upside earnings.

A Saucerful of Secrets

A Saucerful of Secrets is not a technical analysis term, it's not the new pot and handle formation. It is the name of one of the best Pink Floyd albums either, one of the two PF albums on which Syd Barrett wove his twisted genius. The album reminds me of the markets in many ways, it takes many twists and turns and the market is most certainly a saucerful of secrets.

With NAB rising steadily off its $26 low 117 months ago to trade above $34.50 now is a good move. Along with three dividends totaling $2.49 plus franking credits, it has been a good investment.

The trust does intend to have numerous banking and investment holding over the years and does plan to hold these shares for a number of years. However, covered call options will be written when the trustees believe the shares have risen close to a short term high. Puts will be written to purchase stocks. Transactions will be executed based on some or all of the following considerations; technical and fundamental analysis, portfolio, tax and income.

Based on the belief that NAB is close to a near term high and it's shares will be able to be purchased for around current values within the next year the trustees will look at possible options priced at 35. As the MACD is rising the trustees are happy to to look for an entry over the coming weeks.


Saturday, January 21, 2006

Pat on the back

The call made back in October was extremely accurate and profitable.

The trusts performace for the year was 5.68% comapred to 1.24 for the cubes and 3.01 for the spiders.

Friday, October 14, 2005

Investing against the tide - Selling Spider Puts

The trustees believe the US stock markets are ready to bounce, possibly quite high to S&P500 1280, over 100 points up form here. The risk profile is good for some speculation. When possible the trustees prefer to get paid up front and carry the risk, hence they have sold put options on the SPY at price points they believe the market will be considerable above at some point in the next five weeks. As options are time wasting even if the market goes down from the current 1176, trustees have 20 points of downside safety and with prepared loss of 4k more downside can be accepted. All advisors including Peter Foley by SMS from Sweden point to a bounce as markets are oversold.
Position was sized in to over several days and is now full allocation. As such it warrants daily monitoring. Trustees note that they DST as trading in US finishes and a more acceptable 8am rather that 6.00pm. Trustees prefer to speculate in US at end of session rather than start, as this provides ability and self control of placing limit orders more aggressively knowing that if not hit can reassess that trading day.

Wednesday, September 07, 2005

Keep your own cofidence

As I’ve said before Talking about your trades while still in them changes your behaviour. So here I am on dangerous ground talking about Telstra. I have bought at least 2/3 in to Telstra, and have just bought more at 4.30. I feel tricked by the government and Telstra, al my assumptions were based on information they both knew to be wrong. Although I have never joined a class action, despite being invited to do so dozens of times, this one really pisses me of. I should have applied that other great rule. If it looks to good to be true then it probably is just that. I’ll buy more if the share drops under 4.10-4.00 still cum dividend.

Tuesday, September 06, 2005

Don't try to catch a falling knife

Cliché’s are a wonderful memory device. If you knew and utilised scores of clichés throughout your life I am sure you would be good at lots things. Original thought is often not required, just RTFM (Read The Forking Manual).

Don't try to catch a falling knife

If a share is falling let it fall. Many shares often have a 100% low to high in a year, so don’t try to catch that falling share, look to buy on a rebound.

Take Telstra for example. It has fallen from over 5.25 to 4.26, but is that cheap, will the market take Telstra even lower. If only investing a little then because of commission you will only have one shot at the price so it is more important to wait for signs of support; like good levels of buying. You dno’t want to plunge in too early with your precious investment capital to cut yourself on that investing knife. Mixing my metaphor, let the knife hit the floor and then pick some shares up.

If you have more capital then you should try to buy in three lots, ie split your money over three buys, to average in a price. This reduces stress on trades, as if you guess to early first up, you are only 1/3 in the trade, if share quickly rebounds you have some money in and can add the rest and so on.

Monday, July 11, 2005

Making money

Making money is easy.
A teenager can do it, or at least make a start.
So if it is that easy why aren't you doing it. Why can't you do it? Are you lazy, sub-normal, disadvantaged, content, too busy, just not your think?

Making money is so easy you can do it while you sleep, you can do it with other people's money. While you sleep I say, are you too lazy for that?

The easiest laziest way to make money is to embrace time. Like a good garden and scores of other things, making money takes time, day to day time and the span of time over years.

If you buy a lotto ticket, then you want more money and yet you are giving money away every time. So the effect is you are getting further away from what you want, by paying for a tiny piece of paper, 'cos that is all you are really ever going to get by playing the lotto. Save that money and all the other money you are wasting, get some money management knowledge by reading or asking and you will be rich in 15 years time, 20 if you are starting from under water.

Money is nothing, but the time it buys is everything. Time is life.

Monday, May 09, 2005

21st Century Alert

But here's the rub: to reverse the trend, prices have to recapture 3 full bricks. That hasn't happened yet on this bounce, but if the SPX moves over 1184 on a closing basis -- intraday doesn't count -- then this chart will form a giant upside white brick. Such big reversals are very important, as they indicate follow-through is coming.

That means a daily close over 1184 on the SPX would likely see prices accelerate to the upside, most likely to 1203 in short order. It would also indicate that the last leg of this cyclical bull market is underway, and higher highs above 1230 by the early summer are squarely in the picture.

Sunday, May 01, 2005

How low can we go

S&P ASX 200^AXJO29 Apr3,983.200-28.400-0.71%

lower she goes, but it is not a time to be aggressive in the market, it is time to wait and assess.

Sunday, April 17, 2005

Tobin Smith -- WaveWire -- Volume 6, Issue 15 (4/13/2005)

"Ladies and gents, you are only as "rich" as you feel.
And without a bulletproof foundation of income and high-dividend-paying equities, you will never feel rich."

Man that guy spews marketing material faster than...but he does have some good takeaway sweet and sour nuggets, education for your financial wellbeing.

Keep This On The Fridge

By Marcus Padley
April 16, 2005

What a life. Pushing electrons around a TV screen. But that's what analysts do. And while we sit in plasterboard boxes in glass towers, outside the world is going on. No amount of electron-shoving would have let you know that in June 2003 "China" was about to happen, that BHP profit forecasts were 100 per cent too low, the price was too low and the return on equity of BHP's Yabulu nickel operation was, in fact, irrelevant. Investing is not about analysing the trees; it's about predicting where the wood is off to, and in Australia, the wood is on the move.

The sharemarket is suddenly falling, not rising. The Reserve Bank has hinted the economy may be slowing, not growing. These are big changes. Falling market. Slowing growth. It means:

· Lock in profits in things that have gone up a lot.
· Sell small trading stocks.
· Sell volatile sectors.
· Sell cyclical sectors.
· Rotate into defensive sectors.
· Rotate into low-risk income stocks.
· Stop giving concept stock the benefit of the doubt.

Sectors to sell include stocks that have risen a lot, are exposed to the economic cycle, have high price-earnings multiples and low yields, priced on hope and glory instead of a boring story:

· Discretionary stocks: Retailers mostly, selling items you don't need.
· Media: Advertising is the first expense to be cut.
· Leisure: People cut back on travel/hotels.
· Builders: House prices drop and builders suffer.
· Transport: At the pointy end of the economic cycle, people ship less goods around.
· Stockmarket-exposed stocks: Obvious - stockmarket falls, stockmarket stocks fall.
· IT: Another expense to be cut in tough times.
· Resources: Exposed to metal prices that are driven by global economic growth.
· Chemicals: Dictated by commodity prices.
· Paper: Paper and pulp prices dictate.
· Biotechs: Priced on irrational exuberance.


On the flip side are defensive stocks, with predictable earnings, steady dividends, monopolies, captive client bases, low P/Es and high yields:

· Food: Everyone's got to eat.
· Booze: Drinking habits are not that cyclical.
· Health care: Everyone still needs it.
· Property trusts: Rents are fixed on long-term contracts, high yields.
· Gambling: Gamblers gamble regardless.
· Utilities: Tend to be priced on valuation and yield. Monopoly customer bases.
· Energy: Like utilities, fairly certain cash flows thanks to monopoly nature of customer bases.
· Banks: Priced on yield, P/E discount to market.
· Telecoms: Theoretically cyclical, though Telstra is pretty defensive at the moment.
· Rural stocks: Priced on drought.
· Oil stocks: Priced on the oil price.

What does this mean to us? Affirms Telstra as a god choice and banks may be worth looking at again.

Friday, April 15, 2005

Is there fear out there

The fear is rising in the US. Here with the ASX200 at
4:07pm4,014.300-68.000-1.67%
down from 4266.9 or 6.3% drop
15 days below the 50 day MA
this could be good for a drop down to the 200 day MA which is still rising. Is destiny 3875?
At this point only those who have entered market in last four months are under water.
Westfield 15.99
Telstra 5.04

Thursday, April 14, 2005

Candlesticks rule and Telstra

ASX200
4,082.300-52.700-1.27%
Back down near the intra day low from a couple weeks back and the lowest closing in almost three months. Intra day is why you must use candlesticks instead of simple line graphs. Line only conveys one piece of information while candlesticks convey four; low high open close.
Hopefully this will bring some fear in to the Aus market, as we are looking to buy.

Telstra firms as the worst comments I have found aren't too bad, Income Investors view is real income has only marginally increased over the last five years. That is true, but it is at least stable has a good dividend and in unlikely to be as effected in a big down turn, compared to banks and shopping centre owners.

Monday, April 11, 2005

ASX Outlook from Dale Gillham 11 Apr 05

When the market confirms the low, you will find many stocks present buy signals, so right now I suggest you use the next few weeks to study the market to find which will be the best to buy. That said, given that the next rise is highly unlikely to go beyond 14 months, I recommend you be more conservative if you leverage your investments. It is generally during the last stages of a bull market when many people get caught out and end up losing money.
http://www.wealthwithin.com.au/pages/default.cfm?page_id=17472

The trustees agree with this outlook and will look to position themselves for gains over the coming months. Concentrated on shares with the greates potential and least risk. Current thoughts have not changed, Opis Fund, Telstra, ANZ, WDC and NAB are on our watchlist. Telstra May 4.94 Puts are looking very attractive, as the trustees would be happy purchasing shares under 5.00.